Consumer Legal Funding Regulation Addresses the Conduct Identified in ATRA’s RICO Report
Rebuttal to the Litigation Financing Discussion in ATRA’s October 1, 2026 Report
Introduction
The American Tort Reform Association’s October 1, 2026 report, Turning the Tables? The Growing Use of Civil RICO Actions by Businesses and Insurers to Respond to Suspected Fraudulent Litigation, raises serious allegations concerning fraudulent personal injury claims, staged accidents, improper referrals, and the involvement of certain litigation funders in alleged fraudulent schemes.
Fraud should be investigated and prosecuted wherever it occurs. The Consumer Legal Funding industry has no interest in defending staged accidents, fabricated claims, kickbacks, improper referral arrangements, or anyone who knowingly participates in fraudulent conduct.
Where the ATRA report goes too far, however, is in allowing allegations involving certain actors to create the impression that such conduct is inherent to Consumer Legal Funding. It is not. In fact, the modern regulatory framework governing Consumer Legal Funding increasingly prohibits the very conduct described in the report.
The Report Uses an Overly Broad Definition of Litigation Funding
A fundamental problem with the report is its use of the broad term “litigation funding.”
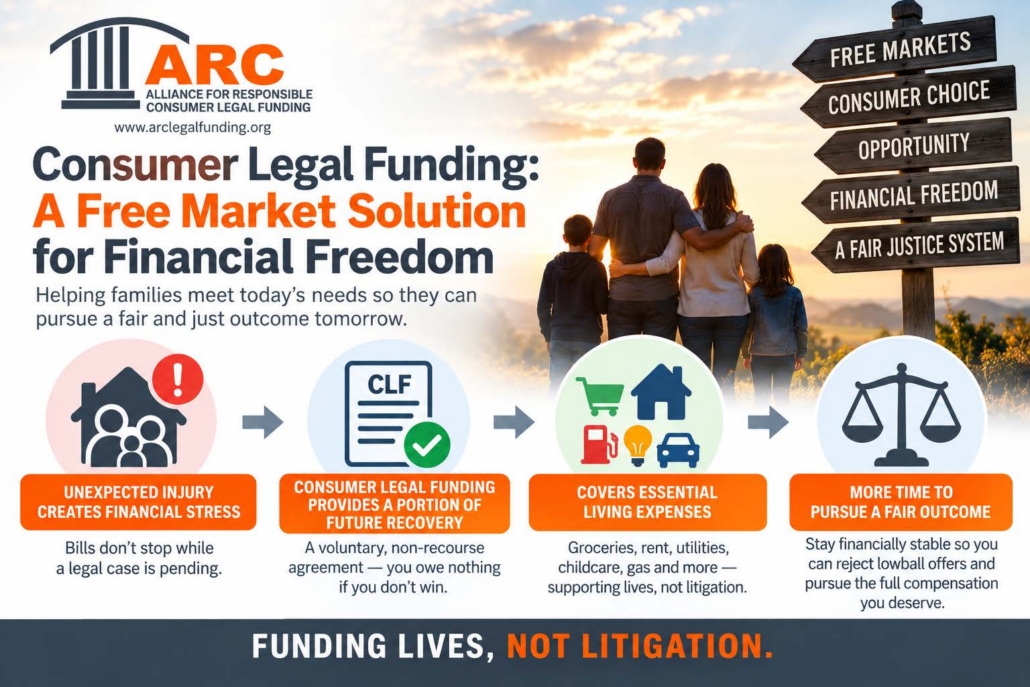
Consumer Legal Funding is a specific financial product. A consumer with an existing legal claim may receive non-recourse funds for personal and household expenses while the claim is pending. Repayment is contingent upon a recovery. If the consumer receives no recovery, the consumer has no obligation to repay the funding company.
Consumer Legal Funding does not finance the prosecution of litigation. Its purpose is to provide consumers with financial assistance for ordinary household needs while they wait for their legal claims to be resolved.
That distinction is important because the ATRA report discusses a broad range of alleged conduct under the general heading of “litigation funding” without adequately distinguishing legitimate Consumer Legal Funding from other financial arrangements.
New York Now Expressly Prohibits Much of the Conduct ATRA Describes
This distinction is especially significant because many of the examples in the ATRA report involve New York and conduct allegedly occurring before New York adopted its comprehensive statutory framework governing litigation funding.
New York law now establishes clear boundaries governing the relationship between a Consumer Legal Funding company, a consumer, and the consumer’s attorney.
Among other protections, the law prohibits improper referral-fee arrangements involving funding companies and attorneys or law firms. It also prevents funding companies from improperly steering consumers to particular attorneys.
New York goes further. A litigation funding company may not influence or attempt to influence decisions concerning the conduct, settlement, or resolution of the consumer’s legal claim. Those decisions remain exclusively with the consumer and the consumer’s attorney.
The law also restricts the use of Consumer Legal Funding monies for the costs of prosecuting the underlying legal claim.
Most significantly in light of ATRA’s allegations concerning fraudulent litigation, New York prohibits a company from entering into a funding contract when it has a reasonable basis to believe that the underlying claim is frivolous, based upon false facts, or otherwise lacks merit.
The result is straightforward: the type of coordinated participation in fraudulent litigation portrayed in portions of the ATRA report is not a permissible business model for a regulated Consumer Legal Funding company operating under New York’s current law.
The Alleged Referral Networks Are Specifically Addressed
Several of ATRA’s allegations depend upon relationships among those who generate claims, attorneys, funding companies, and consumers.
Modern Consumer Legal Funding statutes are specifically designed to separate these functions.
Under New York law, a funding company cannot pay an attorney or law firm for sending it a consumer. It cannot accept improper compensation in return for referrals. It cannot steer the consumer to a particular lawyer. And it cannot control the underlying legal claim.
These are not simply disclosure requirements. They are substantive restrictions designed to prevent a funding company from becoming an active participant in generating or controlling litigation.
That is an important distinction missing from the ATRA discussion.
Providing a consumer with non-recourse funds for rent, utilities, groceries, transportation, and other household expenses is fundamentally different from participating in the creation or prosecution of a lawsuit.
Other States Have Adopted Similar Safeguards
New York is not an isolated example.
Kansas HB 2518 provides an especially clear illustration of the direction states are taking. Kansas prohibits a Consumer Legal Funding company from paying or accepting certain referral fees, influencing the conduct or settlement of the underlying claim, and using Consumer Legal Funding monies to pay court costs, filing fees, or attorney fees.
Most importantly in responding to the allegations raised by ATRA, Kansas expressly prohibits a funding company from colluding with or knowingly assisting an attorney or law firm that is enticing a consumer to bring a claim the company knows, or has reason to know, is fabricated or otherwise not brought in good faith.
The Kansas statute also draws an important definitional line. Consumer Legal Funding is funding used for personal or household expenses. It is not funding for expenses directly related to prosecuting the consumer’s legal claim.
Ohio’s HB 105, effective October 6, 2026, follows the same general regulatory approach. Ohio establishes protections addressing improper referral relationships, funder interference with the underlying legal claim, and collusion involving fabricated claims.
These statutes demonstrate an important point missing from the ATRA narrative: policymakers are not ignoring potential abuses. States are creating regulatory boundaries specifically designed to separate legitimate Consumer Legal Funding from fraudulent claims, improper referrals, attorney conflicts, and funder control over litigation.
Consumer Legal Funding Does Not Finance Litigation
The distinction between funding a consumer and funding litigation itself is essential.
Legitimate Consumer Legal Funding provides consumers with funds for personal and household needs such as rent or mortgage payments, utilities, groceries, transportation, and other everyday expenses while a legal claim is pending.
The product does not exist to pay lawyers or finance the prosecution of litigation.
That distinction is particularly relevant to ATRA’s suggestion that litigation funding provides a financial infrastructure capable of “underwriting and scaling questionable litigation practices.”
Providing $3,000 to $5,000 in non-recourse funds to an individual consumer for household expenses is fundamentally different from financing a lawsuit.
The consumer must already have a pending legal claim and be represented by an attorney. The funding company does not create the claim, prosecute the claim, control the attorney, or determine whether the consumer accepts a settlement.
Conflating these activities creates a misleading picture of what Consumer Legal Funding actually is.
ATRA’s Own Report Recognizes the Role of State Regulation
Significantly, ATRA’s report itself acknowledges that states are responding legislatively.
In its “Legislative Interventions” section, the report recognizes that a growing number of states have enacted laws regulating litigation funding practices.
That acknowledgement is important.
The appropriate policy response to improper conduct is exactly what states such as New York, Kansas, and Ohio have done: establish clear rules defining Consumer Legal Funding, prohibit improper relationships and conflicts, preserve attorney and consumer control over legal claims, establish enforcement mechanisms, and punish companies that violate those requirements.
The existence of allegations concerning past misconduct is not an argument against regulation. It demonstrates why regulation matters.
Regulation Creates a Bright Line
There should be broad agreement over several fundamental principles.
- A Consumer Legal Funding company should not participate in staging an accident.
- It should not knowingly fund a fabricated claim.
- It should not pay someone to manufacture or generate a fraudulent claim.
- It should not pay an attorney for referring a consumer.
- It should not tell an attorney how to litigate a case.
- It should not control whether a consumer accepts or rejects a settlement.
- It should not provide funding when it knows, or has reason to know, that the underlying claim is fabricated or fraudulent.
Modern Consumer Legal Funding statutes increasingly make these boundaries explicit.
The important distinction, therefore, is not between litigation with funding and litigation without funding. It is between lawful Consumer Legal Funding and fraudulent conduct.
Fraudulent conduct does not become Consumer Legal Funding simply because money changes hands.
The Industry Should Be Judged Under Today’s Regulatory Framework
Many of the allegations highlighted by ATRA concern conduct that allegedly occurred before the enactment of today’s regulatory safeguards.
That timing matters.
It is misleading to rely upon historical allegations as evidence of what a regulated Consumer Legal Funding company is legally permitted to do today without acknowledging the significant statutory changes that have occurred.
New York now has a comprehensive statutory framework governing the industry. Kansas has enacted detailed Consumer Legal Funding legislation. Ohio’s HB 105 became effective October 6, 2026. Other states have likewise enacted Consumer Legal Funding laws establishing clear boundaries for industry conduct.
Those laws matter.
If a company violates them, regulators should enforce them. If someone stages an accident, fabricates an injury or claim, pays an illegal kickback, or knowingly assists fraudulent litigation, existing civil and criminal laws should apply.
But those acts should not be attributed to an entire regulated industry whose legitimate product is fundamentally different: providing non-recourse financial assistance to consumers with pending legal claims so they can meet ordinary household expenses while their cases proceed.
Conclusion
ATRA is correct about one fundamental point: fraud has no legitimate place in the civil justice system.
Where its analysis becomes incomplete is in failing to adequately distinguish alleged fraudulent conduct from regulated Consumer Legal Funding and in failing to fully account for how substantially state law has changed.
The allegations ATRA identifies do not demonstrate why Consumer Legal Funding should be restricted. They demonstrate why clear and enforceable regulation is important.
New York, Kansas, Ohio, and other states have increasingly drawn that line. Their laws prohibit improper referral arrangements, preserve consumer and attorney control over claims, address conflicts of interest, restrict the use of Consumer Legal Funding for litigation expenses, and, in some jurisdictions, expressly prohibit participation in fabricated or bad-faith claims.
The answer to fraud is enforcement against fraud.
It is not eliminating or restricting a legitimate financial product that allows an injured consumer to pay rent or a mortgage, keep the lights on, buy groceries, maintain transportation, and meet other household expenses while waiting for a legal claim to be resolved.
Consumer Legal Funding: Funding Lives, Not Litigation.